Просмотр новости
Найдите то, что Вас интересует
 Спутники
 РН
 SpaceX
 Роскосмос
 NASA
СпутникиРНSpaceXРоскосмосNASAThe merchant swears the refund went out; your account shows nothing. Both can be true while the money moves along a rail. Here is how to track it by card, ACH, and wallet.
The post Refund ‘Sent’ but Not in Your Account? A Tracking Sheet first appeared on VentureLab.
The merchant swears the refund went out days ago. Your account shows nothing. Both statements can be true at the same time, because a refund is not a single event, it is money moving along a specific rail with its own timeline and its own tracking number. Knowing which rail you are on is how you stop guessing.
Refunds route through cards, bank transfers, and wallets or buy-now-pay-later plans in 2026, and each behaves differently. A card refund and an ACH return follow different clocks and carry different reference numbers, so generic advice like “wait three to five days” tells you almost nothing about your actual case.
This is a tracking template. Identify the rail, capture the right reference number, know the normal timeline, and you will know exactly when a missing refund has crossed from “still processing” into “time to escalate.”
Bottom Line FirstWhen a merchant says your refund was sent but it is not in your account, first identify the rail it travelled: card, bank ACH, or wallet and buy-now-pay-later. For a card refund, ask the merchant for the ARN, the acquirer reference number, and give it to your card issuer to open a refund trace. For an ACH refund, capture the trace number and expect a different, often slower timeline. For a wallet or BNPL refund, confirm whether the money returns to your original funding source or your balance, since that changes where to look. Standard card refunds commonly take 5 to 10 business days to post, so log the date the merchant issued it, the rail, and the reference number, then escalate to a dispute if it passes the normal window.
Table of Contents
A refund has stages, and the merchant only controls the first one. They approve it, create a refund transaction, and hand it to their payment processor, which takes a few business days on its own. From there it travels the rail back toward you, and only at the end does it post to your account. So “we sent your refund” usually means “we started it,” while your balance reflects the very last step. The gap between those two is where the anxiety lives.
That gap is normal up to a point and a problem past it. The way to tell the difference is to stop watching your balance and start tracking the transaction, with the reference number that matches your rail.
First, identify the railEverything downstream depends on this, so pin it down before anything else. Ask the merchant, or check your original receipt, for how the refund was issued. There are three common rails, and each has its own clock and its own tracking number. Mixing them up is why people wait on the wrong timeline and call the wrong company.
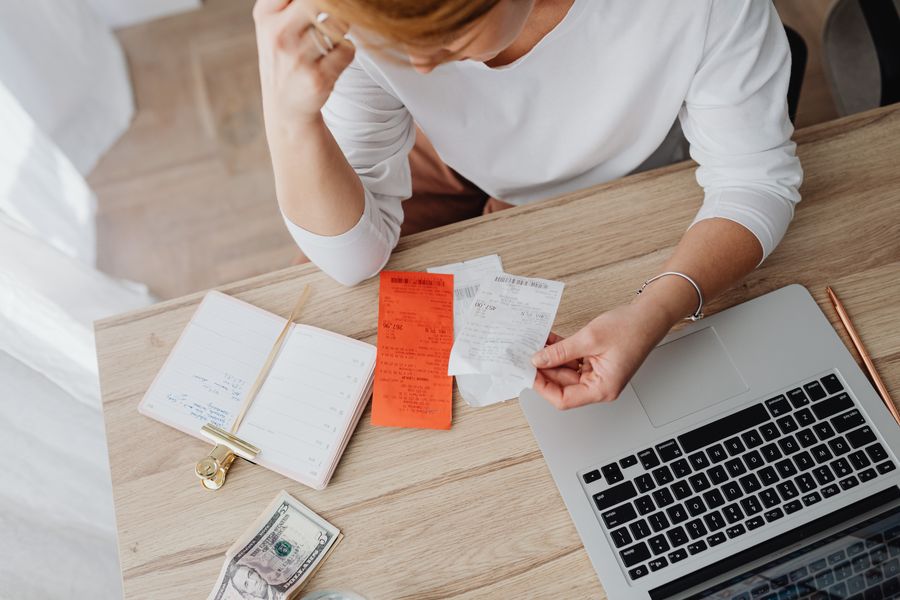
Most consumer refunds ride the card rails, and the number that matters is the ARN, the acquirer reference number. If the refund happened within a day or two of the original charge, it may post as a reversal, where the original charge simply disappears rather than a separate credit appearing. Standard card refunds usually take about 5 to 10 business days to reach you after the merchant issues them, as issuers like Citi describe in their overview of how credit card refunds work.
When the merchant insists it is done and your bank sees nothing, ask for the ARN and give it to your card issuer to open a refund trace or research request. That single number often breaks the stalemate, because it lets your bank locate the transaction the merchant already sent. The refund mechanics differ slightly by processor, a distinction our comparison of Stripe versus a merchant account for refunds gets into.
ACH and bank refunds: capture the trace numberIf the refund came back as a bank transfer rather than to a card, you are on the ACH rail, which runs on its own schedule and can move or bounce for different reasons. The reference to capture here is the trace number, and if the transfer failed, it comes back with a return reason code. When a bank refund shows as sent but has not landed, the pattern mirrors our walkthrough of an ACH transfer marked completed but not received. Log the trace number and the date so you can ask your bank to locate it precisely.
Wallet and buy-now-pay-later refunds trip people up because the money may not come back the way it went out. A refund can return to your wallet balance rather than your bank, or a buy-now-pay-later provider may adjust your remaining plan instead of pushing cash back immediately. Confirm the destination before you conclude anything is missing, and if a plan is involved, our rundown of BNPL chargeback questions covers how those refunds and disputes behave.
The rail-by-rail tracking sheetBuild a row per refund with these columns, and a missing refund becomes a status you can read at a glance.
| Rail | Typical timeline | Reference to capture | Where to escalate |
|---|---|---|---|
| Card (credit or debit) | About 5 to 10 business days | ARN (acquirer reference number) | Card issuer refund trace, then dispute |
| ACH or bank transfer | Varies, often slower than cards | Trace number, return code if failed | Your bank, then the sender |
| Wallet balance | Often faster, sometimes instant | Wallet transaction ID | Wallet provider support |
| Buy-now-pay-later | Plan may adjust before cash returns | Order and plan reference | BNPL provider, then card behind it |
Tracking first, disputing second. Once a card refund passes its normal window and an ARN trace has not resolved it, you can dispute the underlying charge with your issuer. There is a clock on this: for billing disputes you generally must contact your card issuer within 60 days of the statement showing the charge, and the issuer then has a defined window to resolve it. The consumer steps for a charge gone wrong are laid out in the FTC’s guidance on being billed for things you never got. Use the trace first, because a dispute is slower and more adversarial than a refund the merchant already sent.
A refund-tracking checklistThis article is general guidance, not financial or legal advice. Refund timelines, reference numbers, and your dispute rights vary by bank, card network, buy-now-pay-later provider, and jurisdiction, and they change over time. Contact your bank or card issuer for your specific situation, and consult a qualified professional before pursuing a formal dispute.
Frequently Asked QuestionsHow long should a refund actually take?It depends on the rail. Standard card refunds commonly take about 5 to 10 business days to post after the merchant issues them, while ACH and bank refunds run on their own, often slower schedule, and wallet refunds can be faster. Log the issue date and the normal window for your rail so you know when it is genuinely late.
What is an ARN and why do I need it?An ARN, or acquirer reference number, is the tracking number for a card transaction. When a merchant says a refund was sent but your bank sees nothing, giving your issuer the ARN lets them open a trace and locate the refund already in transit. It is the single most useful thing to request from the merchant.
The merchant says it is refunded but my bank has nothing. What now?Ask the merchant for the reference that matches the rail, an ARN for a card refund or a trace number for a bank transfer, then ask your bank to open a refund trace or research request using it. That usually breaks the stalemate without a formal dispute, because it points your bank to the exact transaction.
Why did my refund go to my wallet instead of my bank?Wallet and buy-now-pay-later refunds do not always return the way you paid. A refund may land in your wallet balance rather than your bank, or a buy-now-pay-later provider may reduce your remaining plan instead of returning cash right away. Confirm the destination before assuming the money is missing.
When should I file a dispute or chargeback?After the normal timeline passes and a refund trace has not resolved it. For card billing disputes you generally must contact your issuer within 60 days of the statement showing the charge. Try the trace first, since a dispute is slower and more adversarial than collecting a refund the merchant already sent.
Practical TakeawayStop refreshing your balance and start tracking the refund like a shipment. Write down the date it was issued, the rail it took, and the reference number that matches, then compare against the normal window for that rail. Most “missing” refunds are simply in transit and will arrive. The ones that are genuinely stuck get unstuck faster when you hand your bank an ARN or a trace number instead of a complaint, and a dispute stays in reserve for the rare case that truly needs it.
| # | Наименование новости | Тональность | Информативность | Дата публикации |
|---|---|---|---|---|
| 1 | You Got Refunded but Your BNPL Balance Didn’t Move: What to Ask | 0 | 6.51 | 17-08-2026 |
| 2 | Refund to a Different Card? Why It’s Risky and What to Do | 0 | 5.28 | 19-08-2026 |
| 3 | Duplicate Pending Charge Refund Timeline: What to Expect | 0 | 6.18 | 13-08-2026 |
| 4 | What to Log Before Your AI Agent Emails Prospects | 0 | 7.31 | 11-09-2026 |
| 5 | Pay Still Going to Your Old Bank? A Payroll Timeline | 0 | 6.24 | 15-09-2026 |
| 6 | Name Doesn’t Match? A Payment Method Exact-Match Checklist | 0 | 10.2 | 18-09-2026 |
| 7 | Email Suddenly Undeliverable: DNS, SPF, and Blocklist Fixes | 0 | 6.72 | 13-08-2026 |
| 8 | Proof of Address Too New? A Recency-Window Calculator | 0 | 8.77 | 23-09-2026 |
| 9 | UTM Attribution Not Working: Fixes for Campaign Reports | 0 | 11.49 | 13-08-2026 |
| 10 | Window air conditioners recalled: See if you’re eligible for a refund | 0 | 5.24 | 24-09-2026 |