Просмотр новости
Найдите то, что Вас интересует
 Спутники
 РН
 SpaceX
 Роскосмос
 NASA
СпутникиРНSpaceXРоскосмосNASAFP Answers: Living in Canada, she can use strategies that may reduce both administrative complexity and tax reporting burdens
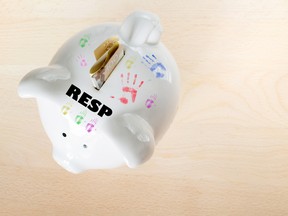 The core benefits of an RESP are tax-deferred growth and government grants, both of which are treated differently under U.S. tax rules. Photo by Getty Images
We independently select everything we recommend. Buying through us may earn us a commission, which supports our work.
Q. I am a Canadian-U.S. dual citizen who lives in Canada. I wish to contribute to a registered education savings plan (RESP) for my two children who are also dual citizens who live in Canada. Although RESPs are non-taxable for my Canadian filing, the U.S. Internal Revenue Service (IRS) requires that I declare the RESP and pay U.S. taxes on the RESP income.
Subscribe now to read the latest news in your city and across Canada.
Subscribe now to read the latest news in your city and across Canada.
Create an account or sign in to continue with your reading experience.
Create an account or sign in to continue with your reading experience.
Canadian financial institutions that hold the RESP do not issue tax slips on any gains within the RESP. I would like advice on how best to report this income, if I keep track of the accounting myself? —Many thanks, Yvonne
FP Answers: As a U.S. citizen resident in Canada, your investment income generated within an RESP is tax-deferred in Canada. However, U.S. persons who are subscribers to RESPs must generally report the income on their U.S. tax returns, Yvonne.
Get the latest headlines, breaking news and columns.
By signing up you consent to receive the above newsletter from Postmedia Network Inc.
A welcome email is on its way. If you don't see it, please check your junk folder.
The next issue of Top Stories will soon be in your inbox.
We encountered an issue signing you up. Please try again
Since RESPs are designed for Canadian taxpayers, financial institutions do not issue tax slips for securities held within these accounts. If you are a U.S. citizen in Canada with an RESP there are strategies that may reduce both administrative complexity and tax reporting burdens.
The core benefits of an RESP are tax-deferred growth and government grants, both of which are treated differently under U.S. tax rules. In your case, Yvonne, you will generally need to report investment income such as interest, dividends and realized capital gains within an RESP on your U.S. tax return. You will also need to track the adjusted cost base and currency conversion for U.S. reporting purposes. RESP government grants such as the Canada Education Savings Grant (CESG) are generally considered taxable to the subscriber for U.S. tax purposes.
Because you are effectively replicating the RESP’s investment activity in U.S. dollars for IRS reporting, simplifying the account structure can make annual reporting much easier. It is also important to note that there are differing interpretations regarding how RESPs should be classified and reported for U.S. tax purposes.
For that reason, I would recommend reviewing RESP reporting requirements with a qualified U.S. cross-border accountant. Accurate reporting and proper interpretation are critical in cross-border planning. You should weigh the benefits of filing independently against the cost and expertise provided by a cross-border expert.
In practice, reporting complexity often comes from tracking transactions related to the underlying investments within the RESP. If the account holds multiple securities, currencies, or income streams, both your reporting obligations and accounting costs may increase significantly. In addition, because these accounts operate within the Canadian marketplace, most available investments are Canadian-domiciled and Canadian-dollar denominated securities.
The IRS generally considers Canadian mutual funds and exchange-traded funds (ETFs), along with certain other managed products, to be Passive Foreign Investment Corporations (PFICs). As a result, enhanced disclosure and additional reporting forms may be required for each individual PFIC held in the account. In many cases, accountants also require supplementary documentation from the fund companies themselves. Some companies provide detailed reporting for U.S. taxpayers. Some do not.
Ultimately, if pursuing a diversified RESP portfolio as a U.S. taxpayer, it may be worth considering either a limited number of PFIC investments that provide U.S. reporting, or instead using U.S.-domiciled ETFs that trade on U.S. stock exchanges. Minimizing the number of holdings may help reduce annual reporting complexity and accounting costs.
You could potentially hold a single U.S.-listed ETF or a Canadian ETF that provides PFIC reporting within the RESP and only need to report one primary stream of investment income annually. For example, an asset allocation or all-in-one ETF held may allow you to generate customized annual reporting showing income and realized gains or losses.
There may also be situations where other investments can still be used efficiently within the RESP. For example, guaranteed investment certificates (GICs) could be appropriate for the fixed-income or cash portion of the portfolio. You could also hold individual Canadian or U.S. stocks.
Although the income may be taxable in the United States, foreign tax credits for Canadian tax paid on other income may help offset or eliminate additional U.S. tax owing on RESP income.
If you can avoid being a subscriber for an RESP as a U.S. citizen in Canada, it is definitely easier. So, if one spouse is a U.S. citizen, the non-citizen spouse can open the account. If you are single, or both spouses are U.S. citizens, you do not have to avoid RESPs. You just need to understand the complexities and consider taking steps to simplify things.
Andrew Dobson is a fee-only, advice-only certified financial planner (CFP) and chartered investment manager (CIM) at Objective Financial Partners Inc. in London, Ont. He does not sell any financial products whatsoever. He can be reached at adobson@objectivecfp.com.
Do you have a question for FP Answers? Email wealth@postmedia.com.
This website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more about cookies here. By continuing to use our site, you agree to our Terms of Use and Privacy Policy.
| # | Наименование новости | Тональность | Информативность | Дата публикации |
|---|---|---|---|---|
| 1 | Ошибка резидента: почему не паспорт определяет ставку налога, а календарь | -1 | 8.9 | 28-08-2026 |
| 2 | Резидент России: как правильно платить налоги, находясь в стране или выехав за границу | 0 | 0 | 06-04-2023 |
| 3 | Are you sure you want to leave the UK to avoid inheritance tax? | 0 | 7.06 | 02-01-2026 |
| 4 | Канада готовится объявить об ответных пошлинах для США 25 августа | 0 | 13.89 | 24-08-2026 |
| 5 | Who is NRI as per FEMA and Income Tax Act? (Latest Rules) | 0 | 11.67 | 26-03-2020 |
| 6 | ФНС РФ: отчет о зарубежных счетах за 2024 г. необходимо представить до 2 июня | 0 | 0 | 20-05-2025 |
| 7 | Как избежать ошибок при подготовке и проверке налоговой отчетности | 0 | 5 | 10-07-2026 |
| 8 | US ethanol exports on track for best year | 0 | 10 | 10-04-2026 |
| 9 | Резиденты будут информировать ФНС о переводе средств через иностранные кошельки с 1 июля | 0 | 0 | 30-06-2021 |